Aircraft Collateral Valuation for Lenders and Lessors
Independent, USPAP-compliant appraisals that help lenders size loans, monitor collateral, and protect recovery value.
Know What Stands Behind the Loan
An aircraft loan is only as strong as the collateral behind it. Market value can shift with supply, maintenance status, damage history, and records quality, and the value a lender can actually recover in a liquidation may be well below fair market value.
Western Aviation provides independent aircraft collateral valuations for banks, finance companies, lessors, and credit teams. Our founder ran an aircraft finance branch for GE Capital Aircraft Financing, so our reports answer the questions credit committees actually ask.
Collateral Valuations Across the Life of the Loan
- Loan origination and underwriting
- Refinancing
- Annual or periodic portfolio monitoring
- Loan modifications and workouts
- Default, repossession, and asset recovery
- Lease returns and remarketing
Values Lenders Need
Fair market value
Orderly liquidation value
Wholesale value (forced liquidation value)
Residual value forecasts
Collateral Risk Factors We Review
- Maintenance status and upcoming major events that affect value
- Engine program enrollment and its effect on value
- Damage history and records gaps
- Market supply and remarketing time
- Aircraft location and condition (onsite appraisals)
How Maintenance Status Affects Collateral Value
Two aircraft of the same model can support very different loan amounts depending on where they are in their maintenance cycles. An aircraft that has just completed a major inspection or engine overhaul is worth more to a buyer than one with those events coming due, because the next owner will pay for them. In a default, that difference shows up directly in what the lender recovers.
Engine maintenance program enrollment matters for the same reason. An enrolled engine usually carries its program coverage to the next owner, while an engine that is not enrolled leaves the overhaul cost with whoever owns the aircraft when it comes due. A collateral valuation should state which applies, and how it affects each value reported.
Records, Location, and Recovery Risk
Collateral is only as recoverable as its paperwork and its location allow. Incomplete logbooks, undocumented repairs, or missing back-to-birth records can lower value and lengthen the time needed to remarket an aircraft. An aircraft based or operated outside the United States can add time and cost to recovery.
Western Aviation notes these factors in the report so the credit team sees not only a value, but the conditions that could affect whether that value can be realized.
Desktop and Onsite Collateral Appraisals
Every collateral valuation is a certified, USPAP-compliant appraisal that meets credit-file requirements. Match the inspection level to the stage of the loan:
| Certified appraisal option | How it fits this service |
|---|---|
| Onsite collateral appraisal | High-value collateral, workouts, and repossessions where condition is uncertain |
| Desktop collateral appraisal | Loan origination and refinancing when condition is known, plus periodic portfolio monitoring |
What Credit Teams Receive
- The values your credit policy calls for: fair market value, orderly liquidation value, wholesale value, and residual value forecasts where requested
- Maintenance status and upcoming events, with their effect on each value
- Records and damage history findings
- Comparable sales and current market supply
- Notes on remarketing time and recovery risk
- A certified, USPAP-compliant report signed by David Fisher, ready for the credit file
Your Appraiser: David Fisher, ASA
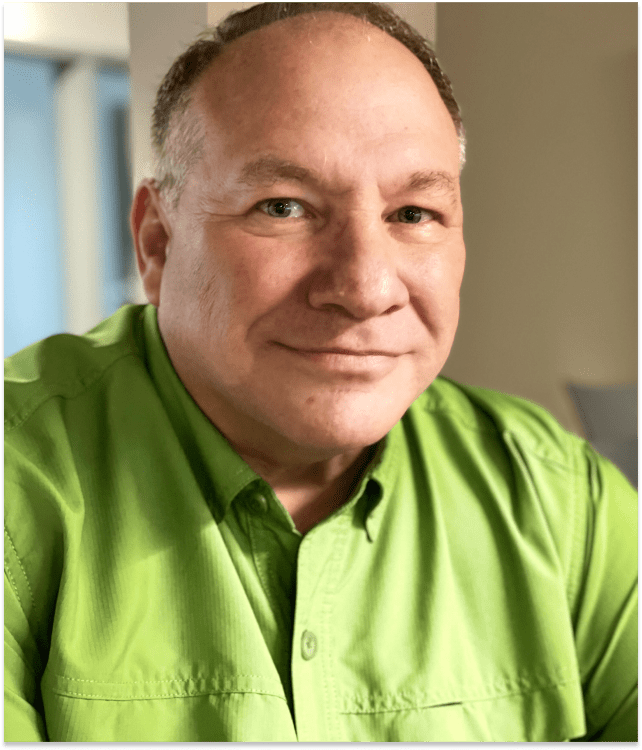
David Fisher is an ASA Senior Accredited Appraiser who appraises both fixed-wing aircraft and helicopters. As an FAA A&P mechanic with Inspection Authorization, he reviews component status and records with a maintenance professional’s eye. He served as a U.S. Air Force crew chief, later worked as a branch manager for GE Capital Aircraft Financing, and has bought, sold, brokered, and appraised aircraft for more than 30 years, across more than 300 transactions.
Frequently Asked Questions
Do you work with lessors as well as lenders?
Yes. Lessors use collateral valuations at lease inception, during the lease, and at lease return, when the aircraft’s condition and maintenance status are compared with the lease’s return conditions.
Can you provide residual value forecasts?
Yes. A residual value forecast estimates what an aircraft is likely to be worth at a future date, such as the end of a loan or lease term. It is reported alongside current values, with the assumptions behind it stated.
What is the difference between fair market value and orderly liquidation value?
Fair market value assumes a normal sale between a willing buyer and seller with reasonable time on the market. Orderly liquidation value estimates what the aircraft would bring in a sale with a limited marketing period, which matters to lenders planning for a possible default.
What is wholesale value?
Wholesale value, also called forced liquidation value, estimates what an aircraft would bring in a quick sale, such as to a dealer, with little or no time to market it. Lenders use it as a worst-case recovery value when sizing loans and planning for a possible default.
How often should aircraft collateral be revalued?
Many lenders revalue annually or when a loan is modified, refinanced, or shows signs of stress. Desktop appraisals make periodic monitoring efficient.
Can you appraise aircraft in repossession or default situations?
Yes. We provide collateral valuations for workouts, repossessions, and remarketing, including onsite inspections when condition is uncertain.
Need a Collateral Valuation?
Tell us about the aircraft, the loan stage, and the values your credit team needs. We respond within one business day.